Retirement & Social Security Specialist
You can claim Social Security with confidence, not guesswork.
Filing at 62 is a decision you live with for life. I show you exactly what each claiming age is worth before you choose.
It's a costly mistake to claim smaller benefits than you've earned.
You deserve better than a default decision made at the Social Security office window. Your filing age, your spouse's record, your pension, and your withdrawal order all move the same number — your lifetime income.
I build the math out in plain English so the choice you make at 62, 67, or 70 is the one you would still make ten years from now.
Start with the free guideThe Critical Decision Window
Why age 62 changes everything
Income Maximization
Claiming at 62 permanently reduces your monthly benefit by up to 30% compared with waiting for full retirement age. We look at what that costs you over a full retirement.
Spousal Protections
Spousal and survivor benefits are coordinated decisions, not separate ones. Timing them together protects whichever of you lives longer.
Tax Coordination
Social Security income interacts with your 401(k) and IRA withdrawals. The order you draw from each account changes what you keep.
Claiming age vs. monthly benefit
- Age 62
- Age 67
- Age 70
Earliest you can file
of your full benefit, permanently
Full retirement age
baseline for those born 1960 or later
Latest it pays to wait
maximum monthly benefit for life
Interactive Tool
Estimate your monthly benefit
Two numbers are all it takes to see what claiming at 62, at your full retirement age, and at 70 would pay you each month.
This is the number shown on your Social Security statement at ssa.gov/myaccount. Don't have it? Use your best estimate.
Your full retirement age: 67
- Age 62
- Age 67Full retirement age
- Age 70
70% of your full benefit · $20,160 per year
100% of your full benefit · $28,800 per year
124% of your full benefit · $35,712 per year
Filing at 62 costs you $15,552 a year compared with waiting until 70 — for life, and every future cost-of-living increase is applied to that smaller number.
Assumptions used in this estimate
- Full retirement age comes from the Social Security schedule for your birth year — yours is 67.
- Claiming early reduces your benefit by 5/9 of 1% for each of the first 36 months, then 5/12 of 1% per month.
- Waiting past full retirement age adds 2/3 of 1% per month, stopping at age 70.
- The monthly amount you entered is treated as your exact full-retirement-age benefit.
- Figures are before taxes, Medicare premiums, and any future cost-of-living increases.
- Not included: the earnings test if you keep working, and spousal or survivor coordination.
Educational estimates only. Your actual benefit is determined by the Social Security Administration.
Benefit Types
More than one kind of benefit
There are six distinct paths to Social Security income. Most households only ever look at the first one.
Retirement Benefits
Based on your 35 highest years of indexed earnings — the record everything else is measured against.
Learn more →Spousal Benefits
Up to 50% of a higher-earning spouse's full benefit, without reducing what they receive.
Learn more →Survivor Benefits
A widow or widower can step up to the larger of the two checks, which is why timing matters for couples.
Learn more →Divorced-Spouse Benefits
If the marriage lasted 10 years or more, you may claim on an ex-spouse's record.
Learn more →Disability (SSDI)
Income before retirement age, and a conversion to retirement benefits once you reach FRA.
Learn more →Dependent Benefits
Monthly payments for qualifying minor children, or adult children with disabilities.
Learn more →Upcoming Seminars
Free retirement & Social Security workshops
Ninety minutes, no sales pitch, and every question answered. Bring your spouse and your most recent Social Security statement.
Thursday, September 17, 2026
6:00 PM – 7:30 PM
Social Security at 62: What It Really Costs
Cranston Public Library — Auditorium · 140 Sockanosset Cross Rd, Cranston, RI 02920
Seats limited to 30 · Map & directions
Thursday, September 24, 2026
6:00 PM – 7:30 PM
Social Security & Retirement Income Strategies
Veterans Fireman's Hall, East Greenwich · East Greenwich, RI
Seats limited to 30 · Map & directions
Monday, September 28, 2026
6:00 PM – 7:30 PM
Spousal & Survivor Benefits, Explained
Veterans Fireman's Hall, East Greenwich · East Greenwich, RI
Seats limited to 30 · Map & directions
Wednesday, October 28, 2026
6:00 PM – 7:30 PM
The 62 / 67 / 70 Decision Workshop
Kirkbrae Country Club · 197 Old River Rd, Lincoln, RI 02865
Seats limited to 40 · Map & directions
Prefer a private session, or want a seminar hosted at your workplace or association? Call 401.304.4409.
Straight Answers
Social Security at 62, 67, and 70 — in plain language
The questions I get asked most often, answered the way I would answer them across the desk. Percentages below assume a full retirement age of 67 (born 1960 or later).
Still have a question about your own record? A short conversation usually settles it.
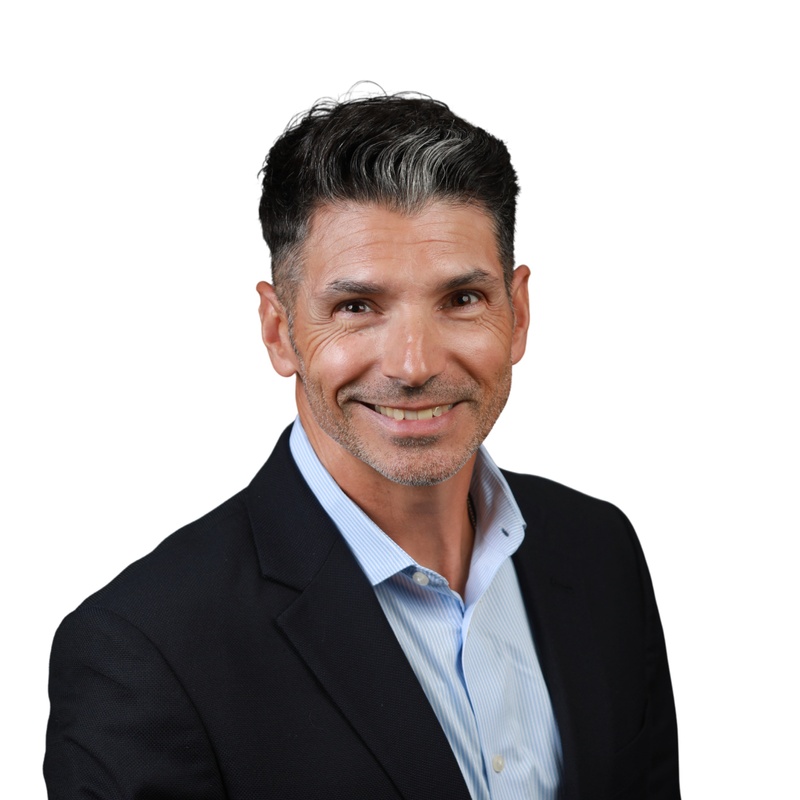
About Corey
Five years of service. Now in your corner.
Corey Lamirande, CFF, NSSA, is a Financial Professional with Gorra Financial Group in Providence, Rhode Island, focused on retirement income and wealth planning. He has built and implemented more than 250 customized retirement strategies nationwide, each designed to maximize income efficiency, manage risk, and align with long-term goals.
He retired from the U.S. Army as a Lieutenant Colonel after five years of service and is a recipient of the Purple Heart. At the culmination of his military career he was responsible for managing funding and resources for large-scale global training exercises. He also served for several years as a police officer in Bristol, RI. Corey volunteers as Community Outreach Coordinator for Rhode Island with the Foundation for Financial Education, a 501(c)(3) nonprofit.
Corey grew up in Johnston, RI, holds a bachelor's degree in Business Management from Bryant University and a master's degree in Business Management from the University of Maryland. He lives in Cranston, RI with his wife and three sons.
Areas of Focus
Retirement income & cash flow, pension analysis, risk management, RMD & tax strategies, legacy planning
Licensed In
RI, MA, CT, NH, SC, GA, MD, VA, FL
Designations
CFF — Certified Financial Fiduciary. NSSA — National Social Security Advisor
The Essential 62 Guide
My plain-English breakdown of the Social Security landscape — written for the years when the decision is actually in front of you.
- Benefit calculation worksheets
- Medicare transition timelines
- Cost-of-living adjustment basics